The AI Bubble: Are We Building the Infrastructure of the Future or the Next Great Capital Destruction?
The technology can succeed while the investment thesis fails. A closer look at AI infrastructure spending, valuations and the economics behind the boom.
Artificial intelligence may well be the most important technological development of our generation.
It has the potential to fundamentally change how businesses operate, how software is developed, how information is processed and how entire industries function.
I have little doubt that AI will create enormous economic value over the coming decades.
But I am becoming increasingly concerned about the amount of capital being deployed to build the infrastructure behind it, the valuations investors are willing to pay, and the assumptions being made about future demand.
There is an enormous difference between believing that a technology will change the world and believing that every company investing in that technology will generate an acceptable return.
History is full of industries that transformed society while destroying significant amounts of shareholder capital along the way.
Railways. Telecommunications. The internet. Renewable energy. And now, potentially, artificial intelligence.
The technology can succeed while the investment thesis fails.
That is the distinction investors need to understand as hundreds of billions of dollars are committed to AI data centres, chips and supporting infrastructure.
The scale of AI investment has become extraordinary
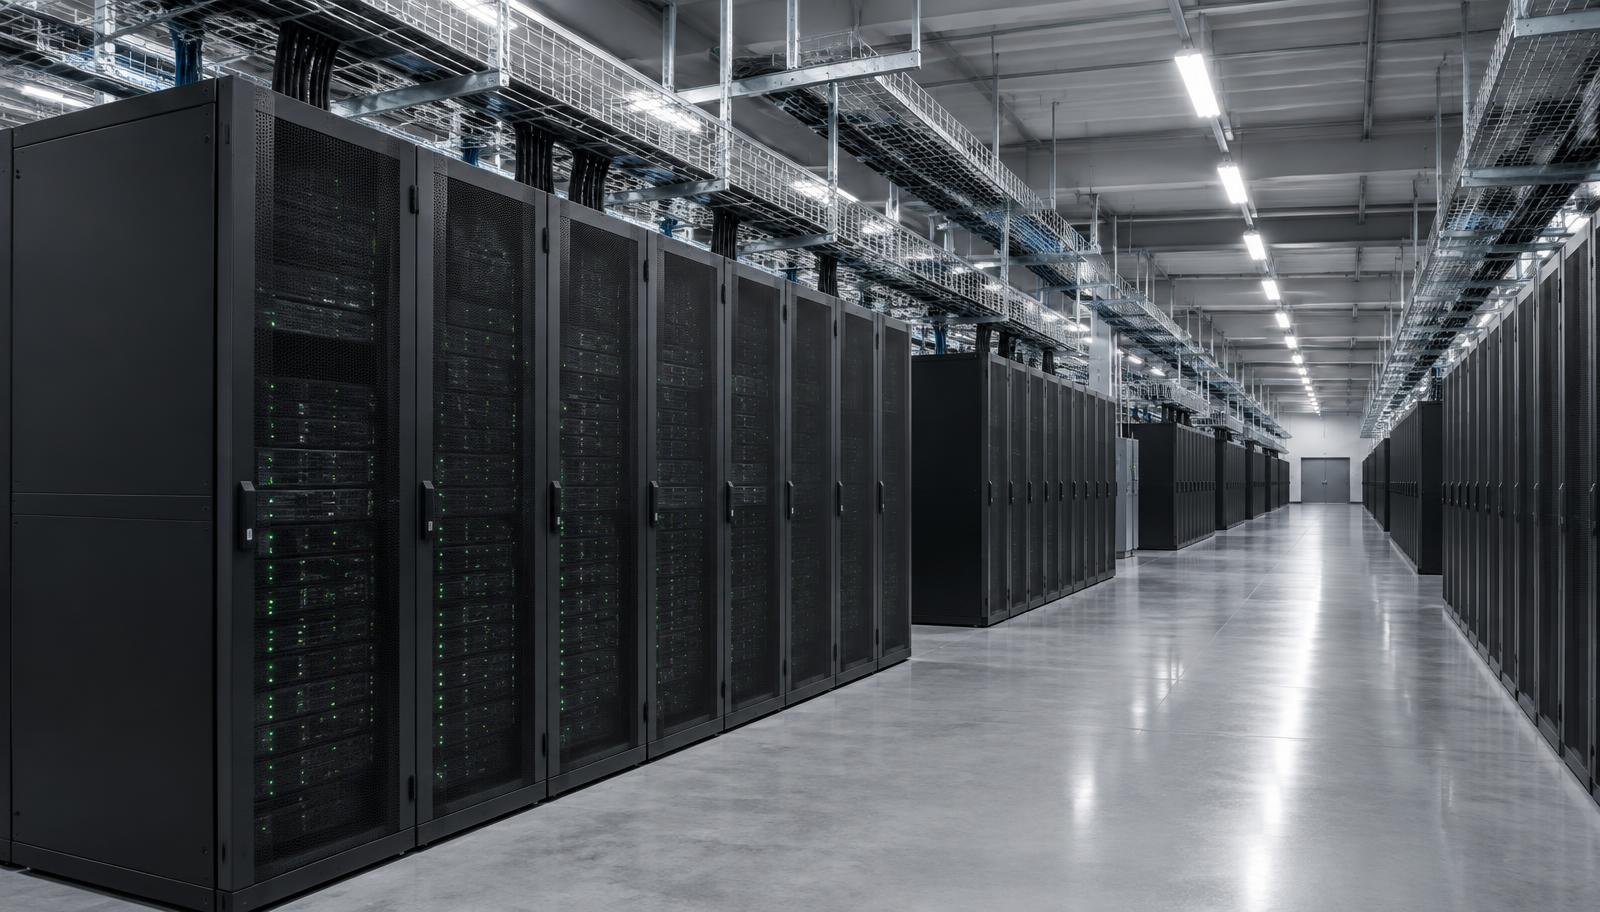
The world's largest technology companies are committing capital at a pace that would have seemed almost unimaginable only a few years ago.
According to the International Energy Agency (IEA), the combined capital expenditure of five large technology companies exceeded US$400 billion in 2025 and was projected to increase by a further 75% in 2026.
That implies annual expenditure exceeding US$700 billion across those five businesses.
To be clear, this is total capital expenditure, not solely spending on AI hardware. Nevertheless, AI infrastructure is a major driver.
The scale of the infrastructure build-out
- 2025 capital expenditure
- US$400bn+
- Five major technology companies
- Projected 2026 increase
- 75%
- IEA estimate
- 2025 data centre power demand
- 485 TWh
- Global electricity consumption
- 2030 projected demand
- 950 TWh
- IEA central projection
Source: International Energy Agency, Key Questions on Energy and AI, 2026.
The investment cycle is no longer confined to chip designers or software developers.
It now encompasses electricity generation, transmission infrastructure, cooling systems, construction, industrial land, financing and enormous data centre campuses.
Capital is flowing into nearly every part of the supply chain.
The obvious question is whether the future demand for AI services will justify the cost of creating this capacity.
And perhaps more importantly: who will actually capture the economic returns?
We've seen this movie before: The dot-com bubble
In the late 1990s, investors correctly recognised that the internet would fundamentally reshape the world.
They were absolutely right.
What they got wrong was how much they were prepared to pay for that future.
Companies raised vast amounts of capital to build telecommunications networks, establish online businesses and expand internet infrastructure.
Many had impressive growth forecasts.
Some had genuinely valuable technology.
Others had little more than an attractive narrative.
When the dot-com bubble burst, investors discovered that future demand for the internet did not automatically translate into profits for every business supplying it.
A particularly interesting parallel is the telecommunications infrastructure boom.
During the period, companies invested enormous amounts in fibre-optic networks in anticipation of rapidly growing internet demand.
Much of that infrastructure eventually became useful.
But excess capacity, aggressive financing and intense competition undermined the economics of numerous early investors.
The infrastructure wasn't necessarily worthless.
The price paid to build it, and the debt used to finance it, were the problems.
This is precisely the distinction I think investors should be considering when evaluating today's AI infrastructure boom.
AI adoption can continue growing dramatically without validating every data centre valuation or capital expenditure forecast.
The most dangerous assumption: Demand will eventually justify the spending
A large portion of today's infrastructure investment is being justified by projections of enormous future demand.
The logic is straightforward.
AI will become increasingly integrated into economic activity. Demand for computing power will rise. Businesses will need more data centres. Therefore, building as much capacity as possible today will create substantial future value.
There is some truth to this argument.
The IEA reported that global data centre electricity consumption rose 17% in 2025, while consumption by AI-focused data centres increased approximately 50%.
Demand is clearly growing.
But this does not settle the investment question.
There are three separate issues:
1. Will demand for AI services increase?
2. Will that demand require the enormous amount of infrastructure currently planned?
3. Will the owners and financiers of that infrastructure earn attractive returns on their investment?
The answer to the first question may well be yes.
The second is less certain.
The third is where I believe investors need to be especially careful.
Growing revenue does not automatically translate into growing profits.
And a rapidly expanding market does not guarantee attractive returns for capital providers.
AI's economics could improve faster than the infrastructure can pay for itself
One of the extraordinary characteristics of artificial intelligence is the pace at which the underlying technology is improving.
Models are becoming more capable.
Hardware is becoming more efficient.
Software techniques are reducing the computational requirements of certain tasks.
The IEA has highlighted exceptionally rapid reductions in electricity consumed per AI task, even as total demand rises because of increased adoption and more complex applications.
This creates a fascinating investment contradiction.
Companies are spending enormous amounts constructing infrastructure based on expectations of future computing requirements.
At the same time, the technology itself is continually becoming more efficient.
It is possible for AI demand to grow substantially while the amount of computing infrastructure required per unit of economic output declines.
Whether total demand ultimately outruns these efficiency gains remains uncertain.
For investors, that uncertainty matters.
Imagine financing a large data centre based on assumptions about future hardware utilisation, rental pricing and demand growth.
What happens if new chips deliver significantly more computing power at a lower operating cost?
What happens if software improvements reduce the amount of computing required for a particular task?
What happens if competitors build enough capacity to push rental prices lower?
All three developments could benefit the end users of AI.
But they may undermine the returns achieved by existing infrastructure owners.
What's good for AI adoption isn't necessarily good for AI infrastructure investors.
The depreciation problem nobody should ignore
Traditional property infrastructure can have exceptionally long economic lives.
A warehouse might operate productively for decades.
A well-positioned office building can be refurbished and leased to successive generations of tenants.
But the computing equipment inside an AI data centre is different.
Advanced chips and servers are exposed to rapid technological obsolescence.
That creates two separate investment risks.
The first is the physical infrastructure itself: land, buildings, power connections, cooling systems and network connectivity.
These may have long useful lives, depending on location, design and future demand.
The second is the computing hardware.
That hardware can become less competitive as new generations of chips offer improved performance and efficiency.
A business that owns the building but leases space to creditworthy customers may have a substantially different risk profile from a business financing billions of dollars of GPUs.
Investors should be extremely cautious about treating these two business models as though they are equivalent.
Why depreciation assumptions matter
Consider a hypothetical AI infrastructure investment containing US$10 billion of depreciable computing equipment.
Illustrative depreciation — five-year useful life
- Annual depreciation
- US$2.00bn
- US$10 billion of computing equipment
- Annual depreciation rate
- 20.0%
- Five-year useful life; zero residual value
Illustrative straight-line depreciation of US$10 billion, assuming zero residual value. Not a forecast of any specific company's accounting treatment or equipment lifespan.
Changing the assumed useful life from three years to seven years dramatically changes annual reported depreciation.
But the underlying economic question remains: how long will the equipment generate competitive cash flows, and what reinvestment will be required to maintain those cash flows?
A company can report impressive EBITDA while still requiring enormous capital expenditure simply to maintain its operating capacity.
That is why the traditional EBITDA multiple can be especially misleading when valuing capital-intensive technology infrastructure.
The financing risk: Are we building an ecosystem that funds itself?
Another emerging concern is the increasingly interconnected relationship between AI technology providers, infrastructure owners, chip suppliers and their financiers.
The industry is seeing arrangements in which technology companies invest in customers, customers commit to infrastructure purchases, and infrastructure providers use those commitments to raise additional capital.
These arrangements can be commercially legitimate.
Strategic investment can help scale new markets, provide customers with necessary financing and support the development of valuable infrastructure.
But they also complicate the assessment of underlying demand.
Reuters reported in August 2026 that some investors were becoming concerned about circular financing arrangements within the AI ecosystem, including substantial financing and lease commitments involving Nvidia and other industry participants.
The critical distinction is between demand ultimately funded by profitable end users and demand supported by ongoing injections of capital from participants within the same investment ecosystem.
If the latter becomes increasingly important, investors need to understand whether reported growth is economically self-sustaining.
A company buying computing services using funds provided by an investor in the computing ecosystem is not necessarily evidence of artificial demand.
But it does make the source and durability of that demand an important due-diligence question.
The real test will be whether customers can generate enough revenue and cash flow to continue purchasing those services without requiring repeated external funding.
Australia's Firmus IPO collapse should be a wake-up call
The Australian market has just provided an extraordinary example of how quickly sentiment can change.
In October 2026, Nvidia-backed Australian AI data centre developer Firmus Technologies abandoned plans for a multibillion-dollar ASX listing after struggling to secure sufficient investor support.
The proposed transaction had been associated with an equity valuation of approximately A$44 billion before efforts to reprice it failed.
Reuters reported that concerns included the scale of the company's financing requirements, its limited operating history and the assumptions embedded in its future growth projections.
Just think about that.
An Australian infrastructure business, backed by some of the most recognisable investors in global technology, was being discussed at a valuation approaching A$44 billion.
Yet Reuters' Breakingviews analysis highlighted that only around 42 megawatts of Firmus's planned 1-gigawatt capacity had been constructed.
There may ultimately be an attractive business within Firmus. Its future results will depend on execution, contractual economics, financing and demand.
But a large proportion of the valuation being contemplated depended on infrastructure that had not yet been delivered and financial performance that had not yet been demonstrated.
That is precisely where the investment risk becomes interesting.
Investors were not simply being asked to value established cash flows.
They were being asked to capitalise an ambitious future.
And when market conditions became less accommodating, that future suddenly became much harder to finance.
What the Firmus experience tells us
The collapse of an IPO does not prove that a company is worthless or that its industry is a bubble.
But it does demonstrate the importance of the assumptions underpinning a valuation.
A project's estimated future value can be enormous.
Yet shareholders only benefit if the business delivers that value after accounting for the cost of completing the development, financing it, maintaining the assets and meeting obligations to creditors and other stakeholders.
This is where I believe the market has occasionally confused the size of the opportunity with the value attributable to equity holders.
A trillion-dollar market opportunity doesn't automatically create a trillion dollars of shareholder value.
Data centres are not all equal
One of the problems with the current enthusiasm is that the market often treats data centres as a single investment category.
They are not.
Different projects can have radically different economics.
| Investment model | Important factors |
|---|---|
| Data centre landlord | Lease duration, tenant quality, property ownership, maintenance capex |
| Powered-shell developer | Grid access, construction cost, development risk, tenant commitments |
| GPU/cloud operator | Hardware depreciation, utilisation, pricing, refinancing and replacement capex |
| Hyperscale cloud provider | Cloud demand, existing distribution, margins, AI monetisation |
| Speculative data centre developer | Planning approval, future financing, tenant demand and construction delivery |
The distinction matters because each business sits at a different point in the risk and return equation.
A fully operational facility with long-term contracts, creditworthy tenants and reliable electricity supply may be a very different proposition from an undeveloped site with a presentation forecasting billions in future revenue.
Likewise, a business renting computing equipment faces a different reinvestment burden from one primarily collecting property rent.
Investors should not apply similar valuation multiples to these businesses simply because they all have exposure to artificial intelligence.
Power might be the real bottleneck
A data centre is not just a building filled with expensive computers.
It requires extraordinary amounts of electricity, cooling capacity and supporting infrastructure.
And those requirements are becoming increasingly difficult to satisfy.
The IEA's 2026 research found that expanding data centre developments were placing pressure on electricity grids, transformer supply chains, generation equipment and planning systems.
It also projected global electricity use by data centres could nearly double between 2025 and 2030.
This is especially relevant in Australia.
The data centre sector is looking to expand rapidly, but suitable land is only one piece of the equation.
Developers need access to sufficient electricity, network infrastructure, construction capability, financing and often substantial upgrades to supporting infrastructure.
Reporting in October 2026 highlighted significant capacity constraints in Sydney's electricity network, with some proposed projects facing delays or expensive network upgrade requirements.
That creates both opportunities and risks.
Existing data centres with secure power connections may possess a genuine competitive advantage.
But businesses developing new capacity could face increasing capital costs, delays and constraints that make their initial financial forecasts difficult to achieve.
The ability to announce a project is not the same as the ability to complete it economically.
The capital expenditure boom may have created its own momentum
There is another dynamic worth considering.
The world's largest technology companies are competing not only for customers, but also for strategic positioning.
No major platform wants to risk being left behind if AI fundamentally reshapes its industry.
That creates an incentive to invest aggressively, even before the eventual economic returns are fully understood.
From an individual company's perspective, the decision may be rational.
If a competitor develops a significant technological advantage, the consequences of underinvestment could be enormous.
But when every participant responds by increasing capital expenditure, the industry can collectively create more capacity than is economically justified.
This is a familiar pattern in capital-intensive industries.
Competition for future market share can drive excessive investment, particularly when financing is available and investors are rewarding growth.
Eventually, the industry has to reconcile the amount of capital invested with the cash flows those investments produce.
That reconciliation may be painful even if demand continues growing.
The bull case: What if the AI investors are right?
It would be a mistake to discuss a potential AI bubble without acknowledging the genuinely extraordinary opportunities created by the technology.
There is a credible argument that current investment levels are justified.
AI could become foundational infrastructure for economic activity, much as electricity, telecommunications and the internet did in previous generations.
The IEA's research shows that actual demand for AI-focused data centre electricity grew rapidly in 2025.
If AI agents become commonplace, businesses increasingly automate knowledge work, and new applications emerge that require substantial computing power, demand could continue to surprise on the upside.
There are also important differences between today's AI boom and the dot-com bubble.
Some of the largest companies funding this expansion already operate enormously profitable businesses with established customers, global distribution and substantial cash generation.
They are not all speculative startups financing themselves exclusively through equity markets.
For investors, the strongest bullish argument is that AI will create such enormous productivity improvements that the infrastructure investment will eventually look modest relative to the economic value generated.
That is possible.
But even in that scenario, the distribution of financial returns is unlikely to be equal.
Customers may capture benefits through lower prices and increased productivity.
Software businesses may capture value through recurring revenue and customer relationships.
Infrastructure providers may face intense competition and continued capital requirements.
AI could be a spectacular success for society and a disappointing investment for some of the businesses building it.
Both outcomes can occur simultaneously.
What would cause the AI bubble to burst?
There doesn't need to be a collapse in AI adoption for AI-related investment valuations to fall significantly.
A change in expectations may be enough.
Consider five potential catalysts:
Slower monetisation: AI revenues increase, but not quickly enough to justify infrastructure spending.
Excess capacity: Too many facilities become operational relative to commercially profitable demand.
Falling computing prices: Technological improvements and competition drive down the revenue generated per unit of computing capacity.
Financing pressure: Higher borrowing costs, tighter credit or weaker investor appetite undermine capital-intensive projects.
More realistic valuations: Investors shift from valuing projected capacity and future revenues towards demonstrated free cash flow and return on invested capital.
These are scenarios, not predictions.
And a correction would not necessarily affect every part of the industry equally.
Some companies could emerge stronger if weaker competitors reduce investment or exit the market.
The outcome will depend on competitive positioning, balance sheet strength and the prices paid for assets.
The Knight Capital perspective: Follow the cash, not the narrative
At Knight Capital, our investment philosophy is grounded in capital allocation and the relationship between business performance and shareholder returns.
That makes the current AI boom particularly interesting.
I believe the underlying technology is genuinely transformative.
I also believe it is entirely possible that substantial amounts of capital are being invested at prices that will ultimately produce poor returns.
Those aren't contradictory views.
When evaluating an AI-related investment, I would focus on a few fundamental questions.
First, who is the end customer? Is demand coming from businesses generating sustainable revenues, or is it materially dependent on externally financed expansion?
Second, what is the return on invested capital? How much cash must be committed before the business can generate an acceptable return?
Third, how much reinvestment will be required? Are current earnings sustainable after accounting for equipment replacement, infrastructure maintenance and changing technology?
Fourth, what happens if industry pricing declines? Does the business possess a meaningful competitive advantage, or is it supplying a service that could become increasingly commoditised?
Finally, what am I paying? Even an exceptional business can be a poor investment if the price assumes everything goes perfectly.
These questions are relevant to a small-cap investor analysing an Australian infrastructure company just as they are to an institutional investor evaluating the world's largest technology businesses.
A simple example of why valuation discipline matters
Imagine two investors assessing the same AI infrastructure business.
Both agree that the company may eventually generate annual free cash flow of $500 million.
One investor assumes this outcome is highly achievable and pays $10 billion for the business.
Another considers the development risk, financing requirements and competitive threats, and decides the opportunity is attractive only at $4 billion.
If the $500 million cash flow materialises, the first investor has paid 20 times that annual cash flow, while the second has paid eight times.
The technology is identical.
The operational outcome is identical.
But the return potential is dramatically different.
That is the importance of price.
No matter how compelling the narrative, the price you pay remains one of the most important determinants of your investment return.
Frequently asked questions
Is AI a bubble in 2026?
There are credible signs of speculative excess in parts of the AI investment market, particularly around capital-intensive infrastructure valuations and aggressive growth assumptions. However, demand for AI services is genuinely increasing, and it would be inaccurate to describe every AI company or investment as speculative.
Are AI data centres a good investment?
They can be, but the economics vary enormously. Investors need to consider electricity access, financing, tenant quality, utilisation, construction costs and ongoing capital expenditure. An existing facility with reliable contracted income has a different risk profile from a speculative development.
Why are technology companies spending so much on AI?
Large technology companies are investing to expand computing capacity, support AI services and protect their competitive positions. The IEA estimates that capital expenditure by five major technology companies could exceed US$700 billion in 2026, based on its 2025 spending estimate and projected growth.
What happened to the Firmus IPO?
In October 2026, Australian AI infrastructure company Firmus withdrew its proposed ASX listing after investors raised concerns about valuation, financing requirements and execution risks. The failed transaction highlighted growing scrutiny of the economics underpinning some AI infrastructure investments.
Could AI experience a crash similar to the dot-com bubble?
It is possible for valuations to fall substantially even if a technology continues to grow. The dot-com period demonstrated that widespread adoption and attractive shareholder returns are not necessarily the same thing. Whether AI experiences a comparable correction will depend on future earnings, infrastructure utilisation, financing conditions and investor expectations.
Final thoughts: The revolution can be real and the bubble can be real
I suspect artificial intelligence will prove to be one of the defining technologies of this century.
The potential applications are extraordinary, and we are probably still in the early stages of understanding how extensively AI will change the economy.
But that doesn't mean every dollar currently being invested will earn an acceptable return.
Some of the most spectacular periods of technological innovation have coincided with enormous capital destruction.
The internet was real.
The telecommunications revolution was real.
The infrastructure was often genuinely valuable.
Yet investors who funded those developments at excessive valuations still suffered substantial losses.
AI may follow a similar path.
The companies that ultimately create the most economic value may not be the ones attracting the most attention today.
And the businesses building the physical infrastructure may not necessarily capture the greatest share of the financial rewards.
For investors, this is a time to remain curious about the technology but disciplined about the economics.
Because being right about the future isn't enough. You also have to be right about the price you pay to participate in it.
About Knight Capital
Knight Capital is an Australian investment firm focused on public markets, business acquisitions, operational improvement and disciplined capital allocation.
Our investment approach is grounded in understanding businesses, assessing the sustainability of cash flows and identifying opportunities where operational execution and thoughtful capital deployment can create long-term shareholder value.
This article represents the views and investment commentary of Knight Capital as at 12 October 2026. It is general information and does not constitute personal financial advice.